Peter Kempthorne
Professor · MIT
Peter Kempthorne is an MIT professor whose research covers Bayesian inference, stochastic processes and statistical methods in finance.
- lectures
- 12
- series
- 1
- hours
- 16
Start here

Series and courses
MIT 18.S096: Topics in Mathematics with Applications in Finance
In these lectures
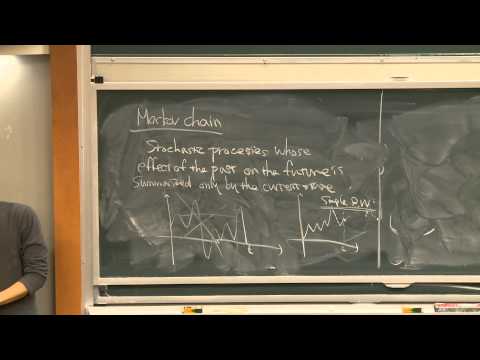
- A stochastic process is formally defined as a collection of random variables indexed by time or as a probability distribution over a space of paths.Stochastic Processes I
- Combining assets with low or negative correlation decreases portfolio volatility without sacrificing expected return.Portfolio Theory
- Least squares estimation is equivalent to maximum likelihood estimation for normal linear regression models.Time Series Analysis I
Draws on
People cited in the lectures, at the moment of the citation.
- Morgan StanleyMorgan Stanley speaker giving a talk on commodity futures and options next Tuesday.
- Christopher SimsNobel laureate cited for econometric work
- von NeumannCo-developer of expected utility hypothesis for decision making.
- Ken AbbottIntroduced Value-at-Risk in earlier lectures.
- A. LincolnCited jokingly regarding quotes on the internet.
- Barr RosenbergDeveloper of the BARRA approach and former UC Berkeley professor
About
Peter Kempthorne is an MIT professor whose research covers Bayesian inference, stochastic processes and statistical methods in finance. Kempthorne's MIT 18.S096 lectures derive Markowitz optimization and Tobin's separation theorem, fit GARCH models and test cointegration.
Taught with
Same subject, Economics & Finance
Connections
17Their places, courses, books and lectures.