Vasily Strela
Professor · MIT
Vasily Strela is a Professor at MIT whose work spans economics, game theory and finance.
- lectures
- 9
- series
- 1
- hours
- 11
Start here
Series and courses
MIT 18.S096: Topics in Mathematics with Applications in Finance
In these lectures
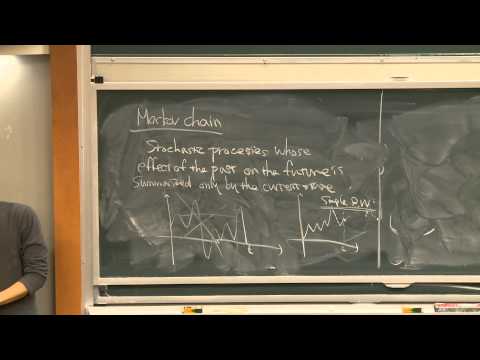
- A stochastic process is formally defined as a collection of random variables indexed by time or as a probability distribution over a space of paths.Stochastic Processes I
- Least squares estimation is equivalent to maximum likelihood estimation for normal linear regression models.Time Series Analysis I
- Value at Risk estimates the worst expected loss over a specific horizon at a given confidence level using order statistics.Value At Risk (VAR) Models
Draws on
People cited in the lectures, at the moment of the citation.
- A. LincolnCited jokingly regarding quotes on the internet.
- Hirotugu AkaikeCreator of the Akaike Information Criterion (AIC).
- Morgan StanleyUpcoming guest presentation.
- Steve RossFaculty in the business school who found the Steve Ross Recovery Theorem.
About
Vasily Strela is a Professor at MIT whose work spans economics, game theory and finance. In MIT 18.S096 he builds risk-neutral valuation from a bookmaker's odds and a binomial replicating portfolio, then derives the Black-Scholes equation with Ito's formula.
Taught with
Same subject, Economics & Finance
Connections
14Their places, courses, books and lectures.